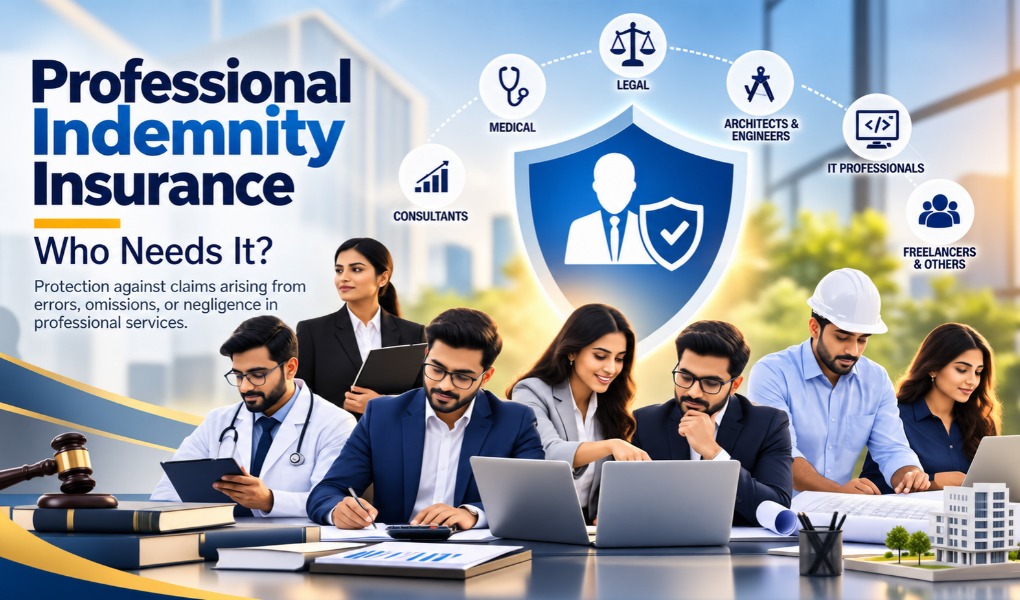
Professional Indemnity Insurance (PI Insurance) provides financial protection to
professionals and businesses against claims arising from errors, omissions, negligence, or
mistakes in the professional services they provide. It can help cover eligible legal costs,
defence expenses, and compensation, subject to the policy’s terms and limits.
Who Needs Professional Indemnity Insurance?
Professional indemnity insurance is particularly relevant to professionals whose clients
depend on their expertise, advice, or specialised services. These may include:
- Doctors and medical professionals: Protection against claims related to alleged
professional negligence or errors. - Lawyers: Coverage for certain claims arising from professional mistakes or
omissions. - Chartered accountants and auditors: Protection against claims involving alleged
errors or omissions in professional services. - Architects and engineers: Useful for claims relating to design errors, incorrect
specifications, or professional oversights. - Consultants: Business, management, HR, financial, IT, and other consultants may
face claims when clients allege that their advice caused financial loss. - IT professionals and software companies: Relevant where professional technology
services are alleged to have caused financial losses. - Financial and insurance advisors: May need protection against claims arising from
alleged errors or inadequate professional advice. - Freelancers and independent professionals: Designers, developers, marketing
professionals, and other specialists may also face professional liability claims.
Coverage differs between insurers and policies. Professionals should therefore check
exclusions, deductibles, coverage limits, territorial restrictions, and claim-notification
requirements before purchasing a policy.
Professional Indemnity vs. General Liability
Professional Indemnity Insurance generally focuses on errors, omissions, and negligence
related to professional services, while General Liability Insurance generally addresses risks
such as third-party bodily injury or property damage. Depending on the nature of a
business, both types of insurance may be relevant.
Conclusion
Professional Indemnity Insurance is an important risk-management tool for professionals
whose advice, expertise, or services could cause financial loss to a client. Doctors, lawyers,
accountants, consultants, architects, engineers, IT professionals, and freelancers are among
those who may consider this coverage. The right policy depends on the profession, services
provided, contractual requirements, and specific risks involved.