How No-Claim Bonus Benefits Health Insurance Policyholders
A No-Claim Bonus (NCB) is a benefit offered by some health insurance policies to
policyholders who do not make a claim during a policy year. It rewards a claim-free record
and can provide additional financial protection when the policy is renewed.
Under an NCB, an insurer may increase the policyholder’s sum insured or provide a
discount on the renewal premium after a claim-free year.
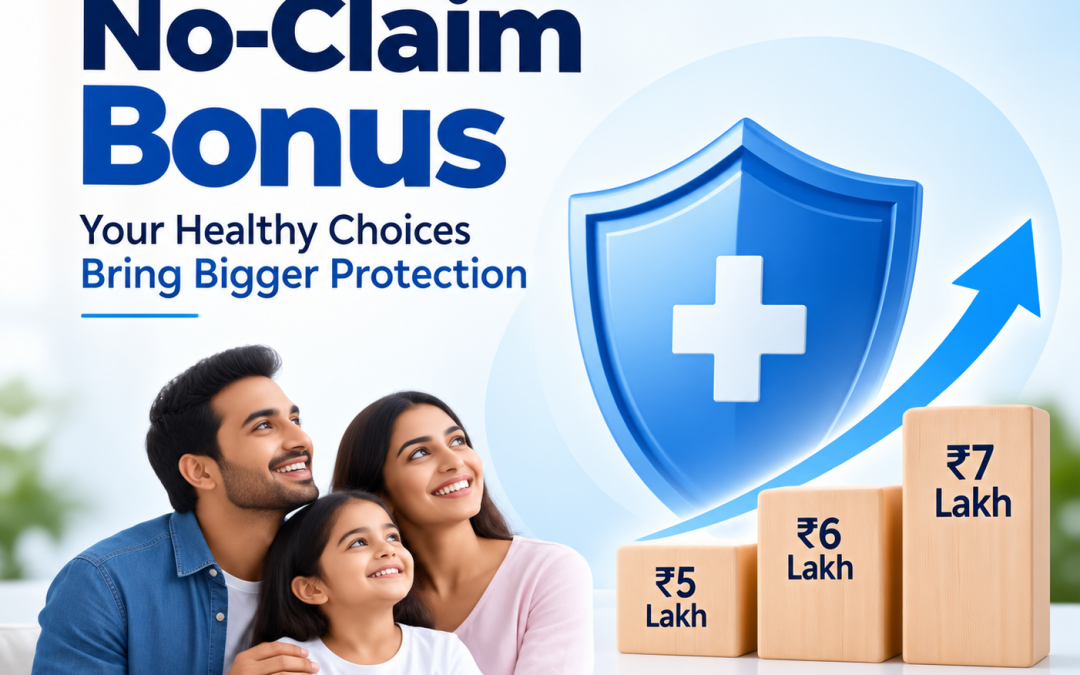
For example, if your health insurance coverage is ₹5 lakh and your policy provides a 20%
cumulative bonus, your coverage could increase to ₹6 lakh after a claim-free year, subject to
the policy’s terms and maximum limit.
Types of No-Claim Bonus
1. Cumulative Bonus:
The insurance coverage increases after every claim-free year. For example, ₹5 lakh may
become ₹6 lakh, then ₹7 lakh, depending on the bonus percentage and maximum limit.
2. No-Claim Discount:
Instead of increasing the sum insured, the insurer may offer a discount on the renewal
premium for maintaining a claim-free record.
Benefits of NCB
- Higher coverage: Your sum insured may increase over time.
- Potential savings: Some policies offer discounts on renewal premiums.
- Better financial protection: Additional coverage can help meet increasing healthcare
costs. - Reward for claim-free years: It provides an incentive to maintain a healthy claims record.
The effect of a claim depends on the terms of the policy. Some insurers may reduce or
remove the accumulated bonus after a claim, while others may protect the bonus under
certain conditions. Therefore, policyholders should carefully check the NCB rules before
purchasing or renewing a policy.
Before choosing a health insurance policy, check:
- NCB percentage offered each year
- Maximum bonus limit
- Whether the bonus increases coverage or reduces the premium
- Conditions applicable at renewal or policy portability
Conclusion: A No-Claim Bonus can enhance the value of health insurance by rewarding
policyholders for maintaining a claim-free record. However, NCB terms vary between
insurers and policies. When comparing health insurance plans, consider the NCB along with
coverage, exclusions, waiting periods, claim settlement conditions, network hospitals, and
premium.